

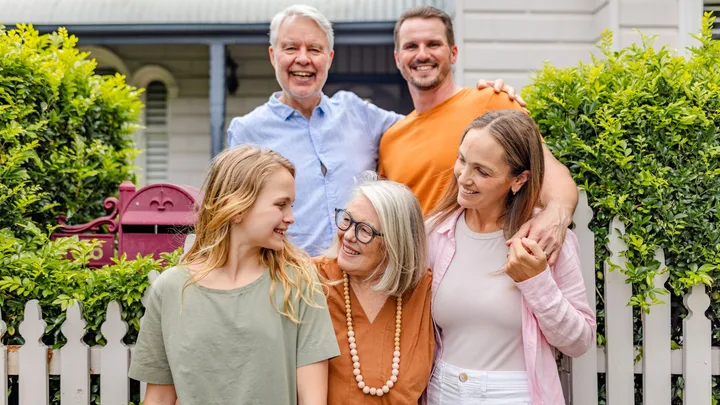
Like many Aussies who plan ahead, David and Margaret had always been careful with money. However as they entered retirement, they found that costs didn’t slow down the way they expected. Along with the usual expenses, they also wanted to take care of including some existing debt and a few improvements around the home.
“We weren’t struggling, we just felt everything was getting harder to manage,” the couple explain.
For Aussie homeowners aged 55 and over, a reverse mortgage can be a way to supplement your retirement income. You only need to access as much as you need, and you will retain ownership of your home throughout the life of the loan.
What it involves
A reverse mortgage allows you to borrow against the value of your home, while you’re living it. The loan only becomes repayable if you sell your home, move into aged care or pass away.
Under Australian law, any reverse mortgage taken out on or after September 18, 2012, must come with a No Negative Equity Guarantee. This means you’re protected from owing your lender more than the value of your home.
Your choice
One size doesn’t fit all so it’s important to make sure any plan you sign up for suits your individual needs. With a Heartland Bank Equity Access Loan, you can choose to receive your funds in a single upfront payment or as regular monthly, quarterly or annual payments. In the case of Margaret and David, one of their biggest concerns was the idea of interest rates building on their home equity over time.
However after a lot of careful discussion, they realised they didn’t need a large amount of money to cover their costs. Instead, they opted for a small initial upfront sum, followed by regular payments that were just enough to take the pressure off their day-to-day expenses and make things more manageable.
Planning ahead
As we get older, a reverse mortgage can be a way to cover additional health and aged care costs that might arise as our support needs change.
For Fred, a reverse mortgage meant that he could access just enough money to make essential renovations that would enable him to live in his home safely and independently.
“I’d been putting the work off for years but I know I couldn’t any more,” he explains.
When the time came to move into aged care, the focus for Sue and her family was to ensure everything was financially in place, without creating extra stress. “There was a lot to think about,” Sue says. “We just needed a way to make things simpler.”
After exploring various options, they decided a reverse mortgage provided a practical solution that helped cover their immediate needs while also planning ahead for the future.
Getting started
A reverse mortgage can feel like a daunting step, so make sure you’re aware of your options and get independent legal advice before signing anything.
The amount you can access depends on your age, property value and the location. Be aware the fee for setting up your loan will come out of the amount you apply for, so it’s important to factor this in to make sure you receive the amount you need.
You can visit Heartland Bank at heartlandbank.com.au to use their free online calculator and to arrange a chat with one of their specialist mortgage consultants. To learn more about managing your money in retirement, you can also visit Money Smart at moneysmart.gov.au
Heart & home
Heartland Bank has helped more than 27,500 Australians stay in the homes they love and live retirement on their own terms. Our customers have used a Heartland Bank Reverse Mortgage to renovate and improve their homes, clear existing debt, buy a new car or simply make their everyday lives a little easier.
Heartland Bank Australia Ltd ABN 54 087 651 750 (AFSL/Australian Credit Licence 245606). Subject to loan approval criteria. Terms, conditions, fees and charges apply. For more information, visit heartlandbank.com.au


Related stories
Native ad body.
Native ad body.
Native ad body.